Thursday, February 8, 2018

Using Miles and Points to Europe

I finally booked the trip I've been saving up for. This is the culmination of everything I've learned doing this silly hobby. I followed four simple steps and boom!

1. Earned 110,000 United miles in the last 12-18 months through flights, dining, and shopping. (I got the MileagePlus Explorer Card in 2016 but used the signup bonus last summer).
2. Mrs. Fox got a Chase Sapphire Preferred and transferred the 50,000-point signup bonus to me.
3. Built up 80,000 points through spending on my Chase Sapphire Reserve, added the 50,000 transfer from Mrs. Fox, then exchanged the 130k points 1:1 for United miles (online and instantaneously).
3. Spent hours researching routes and dates, and finally had to call due to glitches. I was worried the Excursionist Perk wouldn't work if I called, but it worked.
4. A nice woman named Trina at United reservations squared me away in about 30 minutes (I always avoid talking to humans and I don't know why; it's pretty dumb and self-defeating).
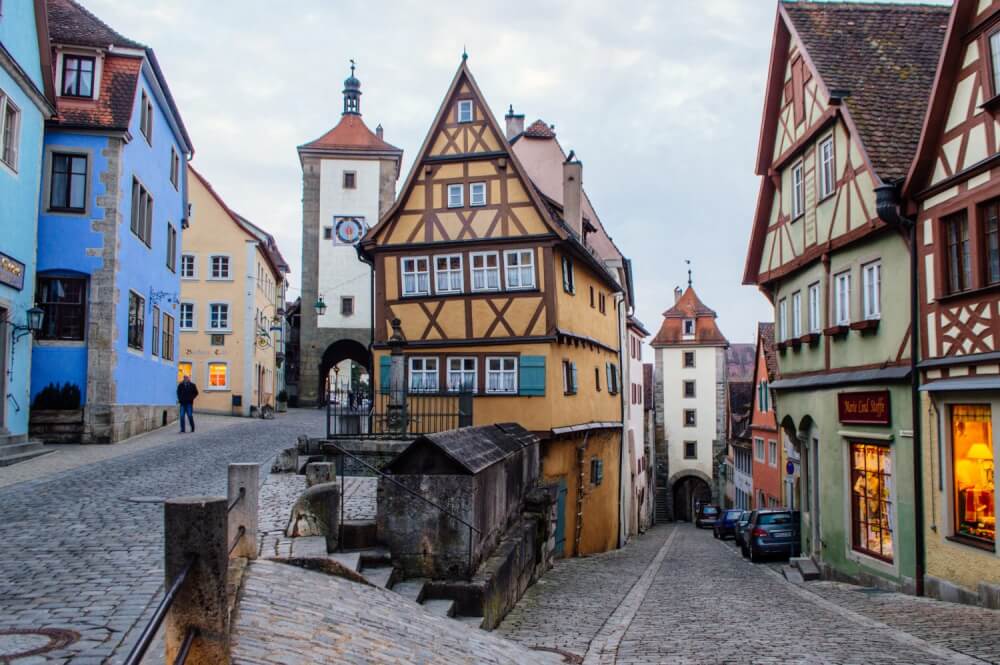
Rothenburg ob der Tauber
So we are flying as such (x4):

1. 30,000 miles saver fare plus $5.60 taxes: 
Washington DC to Frankfurt, Germany, a nonstop overnight redeye.

We'll rent a car and spend a few days revisiting the sights and restaurants (and restaurants) in Germany, where we lived from 2002-06 (and had our first kid, and made our second kid). I learned that one-way rentals within the same country cost about the same, which is different from the U.S. So that will help keep us from retracing our steps, eliminating the need to lay bread crumbs across Germany so we can find our way back to Frankfurt. We'll eat the bread and fly out of Munich.

2. Zero (!) miles plus $45 taxes using Excursionist Perk*:
Munich to Bilbao, Spain.
No, it's Bil-bao!

Bilbao is about 4 hours from Bordeaux in France where we'll spend a week with my parents who are celebrating their 50th anniversary this year, as well as my siblings and their families. We'll rent a car, about $140 for the week, using Chase or Amex points if it makes sense; otherwise we'll use real money.

3. 30,000 miles saver fare plus $113 taxes:
(1) Bilbao to Munich, 1 hr layover
(2) Munich to London, overnight layover
(3) London to Washington, DC.

In London, I'll use hotel points or pay a cheap weekend fare. There won't be time to see the city but my kids can hear the King's English and say they've been to Great Britain. I loved visiting England and Ireland from Germany because it was so nice to hear people around me speaking a language I could understand.

There aren't many layovers, but while we're waiting for flights, we'll be in the lounge eating free food. 

The Damage/ Analysis of Value

For travel worth a minimum of $5,000:
(4 roundtrip tickets at $1000 each plus 4 intra-Europe one-ways worth $250 each)

240,000 miles plus $604 in taxes

$4396.00 / 240,000 miles = 1.83 cents per mile

The Points Guy does a monthly valuation for points and miles. They value United miles at 1.4 cents each. So I got a good deal by that metric, thanks to the Excursionist Perk. That helps the main in me feel clever, but even if I'd gotten less than 1.4 cents a mile, we're taking an awesome trip for $604!

What is this Excursionist Perk of which you speak, dude? In short, for award travel from one continent to another, United allows you one free* flight within that region. It is pretty complicated and explained in detail here.


*you always gotta pay the taxes; taxes are, after all, the only slightly more popular of life's two certainties

Things I learned
(I know United best but most of these lessons are applicable to other airlines)

1. Book as early as you can. The airlines dedicate a limited number of seats to award travel. Having a United credit card and having status opened more seats to me, but it was still challenging, as my return itinerary demonstrates. Virtually every return trip involved ridiculous itineraries and multiple stopovers to get the saver fare (30k vs the usual 70k miles for economy). It's a weekend in peak season. If I'd have booked 6+ months in advance or even returned mid-week, there would have been better options.
2. They say the toughest way to earn miles is flying. The Mileage Plus Shopping Portal, the Mileage Plus dining program, and even the Mileage Plus X app helped me accrue miles. Oh, and I flew a little, too.
3. Be flexible. I'd have preferred to fly into and out of Bordeaux. To do so would have required an overnight layover in Istanbul airport- where an terrorist attack killed 45 people in 2016! Yeah, those fares are cheap for some reason. It's worth a 4-hour drive along the Atlantic Coast to be less of a target.
4. If you wanna lose weight, try this 1 weird trick.

Conclusion

I was joking about it being simple: it takes some work, and there are challenges.
1. It takes a few months to earn miles and meet minimum spending requirements.
2. It takes years and the right combination of genetics to create and rear four children, three of which will all require braces within a year of one another, enabling you to easily meet those minimum spending requirements.
3. It's tough to find a wife who is willing to use any credit card you hand her. I'm joking about that, too, of course- everybody knows women be shoppin'. Thanks, Mrs. Fox! I'll bring you back some wine and at least two of those three children!

Women be shoppin'! You can't stop a woman from shoppin'!

Thursday, February 1, 2018

Amazing new bottle of weight loss medication. Order today!

Nassim Taleb's Antifragile: a book review

Nassim Nichloas Taleb is an incredible thinker and writer. His book "Antifragile" is a delightful blend of ecomomics, philosophy, and life advice.

I read his first major work "Fooled by Randomness" (also the title of his website) in 2009, and his second "The Black Swan" shortly after. But his magnum opus to date is "Antifragile." 

First, the title refers to his thesis that the best systems or organisms (or economies) thrive on stressors. Antifragile things are not merely robust or resilient: the stress/shock makes them better and stronger, hence the term Taleb coined to describe the opposite of fragile. Most everything in the book riffs off of that premise. Below I discuss a few lessons from the book which have influenced me. 

Wu-wei (wait and see)

Wu-wei translates to "without action, without effort, or without control." I think of it as "actively doing nothing." 

"Hell, you don't need a million dollars to do nothing," said the neighbor from Office Space. Not that kind of nothing. 

Wu-wei is a conscious decision to not act, to wait, see what plays out. I do this all the time, and not always because I'm procrastinating. Some problems work themselves out without any intervention on my part. One would think this doesn't apply to plumbing, and it usually doesn't when you have a major leak. But even minor leaks fix themselves sometimes: rust or corrosion forms, and the pinhole in your pipe closes. Just this week I recommended a friend buy Ford stock: it's got a great dividend and Wall Street hates it for irrational and temporary reasons. The friend has hesitated, and Ford's stock has continued to drop. By not following my advice, my friend has saved money. Hmm...

Medical iatrogenics versus "via negativa" 

To solve a medical problem, rather than add a pill (intervention or iatrogenics), the right approach might be to remove something (via negativa). Remove a food from your diet, remove a stressor from your life. There is really something to removing or reducing food (salt, caffeine, or sugar).

Taleb is not anti-intervention, he just wants people to recognize that everything in life has trade-offs. The medical word for these is "side effects." I had knee surgery in 2014 and the doctor prescribed me hydrocodone, an opioid of the sort that is highly addictive. The warnings label included constipation, dizziness...I could have sworn it even said something about paranoia! (But maybe I'm just being paranoid). With Taleb's philosophy fresh in my mind, I decided that the known - "my knee hurts" - was a better side effect than whatever would come from taking hydrocodone, so I flushed them all (sorry, fish!) and ate Motrin every four hours (sorry, stomach lining!).

The writer and economist Thomas Sowell said, "There are no solutions in life, only trade-offs." These are words I live by. Usually it is a politician telling you he can solve a problem. "Tax the rich a little more and everyone can have free college."


My aforementioned knee surgery didn't help me at all. My knee still hurts and swells and I can't run. I went through a few months of pain and physical therapy. I consider the physical therapy a positive in that my leg got stronger and I lost weight doing it. But essentially I chose medical intervention and it didn't help a whit. 

Oh, well! A knee is fairly minor, and so are the risks of knee surgery. But what if it's your brain, or your reproductive system? (These are separate organs in females, generally not so much for males). Always remember that the dentist or surgeon is not necessarily an uninterested party. Your months of pain may be a 50/50 proposition in which the only guarantee is that it will help buy the surgeon a nice boat.

The Paleo diet (shocking the body)

My experience with weight control is that it's 90% diet and 10% exercise. In other words, removing something- extra sugar and calories- is nine times more effective than adding something- exercise. But--there''s always a "but"-- adding even a little exercise is some sort of key that unlocks your body's ability to lose weight. Shortly after my knee surgery, I decided I was tired of my weight- 210 at the time. In about six weeks of eating (almost) no sugar or bread, I lost 15-20 pounds and bought new pants. The only exercise I did was physical therapy 2-3 days a week, which consisted of 15 minutes on a bike or rower followed by various leg weightlifting tortures.

Epilogue: I'm now 215 and in my third year of fixing to start a new diet any day now.

Placing many small bets 

Any Army officer knows that risk is a function of the following:

(probability of event occurring) x (impact)

In your investing life, Taleb advocates placing small, low-probability, high-payoff bets to give you more opportunities to win and also minimize your downside (risk). Ask yourself, what's something that's possible but unlikely, but if it happened would have a huge impact? Taleb did this himself by betting against the banks in the mid-2000s when the housing bubble was in full ridiculousness. He didn't go all-in, and you don't have to either: he just made small bets, some of which paid off in 2008-09 when banks that had been built on garbage mortgages collapsed, requiring taxpayer bailouts.

If you think things like this don't happen, imagine if November 2016, you placed a bet that Donald Trump would beat Hillary Clinton in the presidential election. Or the Patriots would come back from a 25-point deficit to win last year's Super Bowl. Both propositions had 20:1 odds or better, but they happened!

My good friend did this a few years ago by putting $5,000 in each of five "penny stocks" his cousin had recommended. Each company had a share price of ~$5. Since he bought them, four of the five stocks have stagnated or drifted toward zero. One, however, is now worth  $60/share. Let's do that math:

               $25,000 invested in 5 stocks (1000 shares each at $5)
               Current value of the 4 bad ones: $10,000 (4000 shares total at $2.50)
               Current value of the good one: 100 shares at $60 = $60,000

Looking at it holistically, he placed 5 low-probability, high-payoff bets. One of them paid off bigly. So he turned $25,000 into $70,000. Had he put all 25,000 into one of the five companies' stocks, he would have had a 20% chance of having $325,000. Sounds good! But-- he would have had an 80% chance of losing all or most of his money. That's more math than any of us care to do, so I'll leave it there.

It's about time I re-read Antifragile. I don't claim to understand it all- and I especially don't claim to have the courage to follow his every proscription. But I find Taleb witty and absolutely original. He calls charlatans what they are. I just learned writing this piece that Taleb's next work is due February 27: yay! It's called "Skin in the Game" and explores his belief that "If you see fraud and don't shout fraud, you are a fraud."

My favorite Taleb observation is that if economists, with their love of efficiency, designed the human body, people would have one lung and one kidney. If that makes you chuckle and think at the same time, you'll understand why I like this guy.

Thursday, January 25, 2018

The Feasibility of Flying to France for Free

So you've read up on the Credit Card Game and the Points/Miles Game. You've read about the pitfalls and and you've decided it works for you. So where to begin? Today we'll discuss airfare. My situation will be specific to United Airlines, but in general the process is similar for every airline.

1. What's your travel goal? A trip to Europe? A week at the beach? Disney World? It's better to have something specific in mind, lest you end up with points and no reason to use them.

I want to take my three big kids to Europe this summer. My parents are celebrating their 50th anniversary and have rented a house in France for a week. It's going to be great, and then for a few days after I want to show them around Spain, or Germany, where I lived from 2002-06. My credit cards and loyalty programs are going to work for me:

1. Airfare. We are flying on United using miles, and will pay only the taxes ($25-50 each way per person). We'll also have one free trip within Europe thanks to United's intriguing Excursionist Perk.

2. Lodging. I don't know where we will stay yet, but I have sufficient point balances with IHG, Hilton, and Marriott to get free nights, thanks to credit cards and hotel bonus point promotions.

3. Free meals and comfort in transit. At every airport, we will have one or more lounge options. I'll leverage my airline status for more comfortable seats, with the potential for an upgrade to business class.

1. The United MileagePlus Explorer Card offers a 50,000-mile bonus for new applicants who use the card to spend $3,000 within three months, and an extra 5,000 miles if you add an authorized user. I got mine in summer 2016 when the bonus was a bit higher, and I've since earned more miles through shopping, dining, and even flights (the cool kids say flying is the hardest way to earn frequent flyer miles). So I've got about 110,000 miles right now, plus 95,000 Chase Ultimate Rewards Points that I've earned. I can swap Chase UR points 1-for-1 for United Miles, so that puts me at 205,000.

Let's do the math:
- Economy Saver flights are 30,000 one way to Europe; 60,000 miles roundtrip, plus $50-100 taxes.
- 60,000 x 4 (me and 3 kids) = 240,000 miles plus $200-400 in taxes.

I was still about 35,000 miles short, so my wife just got the Chase Sapphire Preferred, which has a 50,000-point bonus. She will transfer those points to me, and then our flights are covered.

There are three major airlines in the US. Each airline has a relationship and 2-4 credit cards each with one of the three major credit card issuers (major as far as credit card enthusiasts are concerned). Decide which airline works best for you, and if air travel is your goal, look at your card options and pick one. My friend wanted to go to France this spring, so he got the American Express Delta Platinum with its 70,000 mile bonus, and just booked a roundtrip flight to Paris for 55,000 miles + tax.

Below is how the card issuers and airlines match up, with the premium "flexible points" card in parentheses which enables you to exchange that credit card's points for that airline's miles. Barclaycard also issues at least one American Airlines-branded card, and the smaller airlines like Southwest, JetBlue, and Alaska also have credit card options.

Chase = United (Chase Sapphire Reserve)
American Express = Delta (American Express Platinum)
Citibank = American (Citi ThankYou Premier)

As I've written before, American Airlines (AA) is a blind spot for me. I know a little about Delta, and a lot about United. If American is your airline of choice, do your research, but in general the experience and benefits will be similar.

One great benefit of the United card is "expanded availability"- this means United saves seats for cardholders that non-cardholders cannot book. So while others might see 2 flight options from, say, Washington Dulles to Paris, I may see 4 options. Other benefits include one free checked bag, priority boarding (i.e. more overhead space when you get on the plane). That makes it well worth the $95 annual fee.

Monday, January 22, 2018

The Overdose Soundtrack of my Life

"Lord, make me middle-class and anonymous."

This is one of the things for which I actually pray. If people still made mix tapes, you could make an excellent mix tape of music by people who have died in this millennium by drug overdose. Below are my favorite songs from the more famous members of this grim club.

Side A: 2000s overdoses
"Would?" by Alice in Chains- Layne Staley (also Mike Starr)
"Punk Rock Girl" by the Dead Milkmen- Dave Schulthise
"Unchained Melody" by the Righteous Brothers- Bobby Hatfield
"Will You Be There" by Michael Jackson
"See You Around" by Vic Chesnutt

Side B: 2010s overdoses
"Big Empty" by Stone Temple Pilots- Scott Weiland
"Heaven" by Warrant- Jani Lane
"Purple Rain" by Prince
"Echo" by Tom Petty (also Howie Epstein of the Heartbreakers)
"Daffodil Lament" by The Cranberries- Dolores O'Riordan
"I Will Always Love You" by Whitney Houston

I love all these songs. I didn't realize some of these people had even died, like the Righteous Brother and Jani Lane. Each of the tracks above is on the soundtrack for a time in my life, or a person, or some defining event.

I am assuming with the angelic-voiced Dolores O'Riordan that it was either suicide or a drug overdose. I find that when no details are given, the cause of death is usually one of the two. Since she died, I have been listening to her albums and watching videos of Cranberries performances. In 2007, I had the good fortune to attend a solo concert in a small venue in Charlottesville. Dolores was small, Irish, feisty, and a total superstar. The charisma radiated off of her. I thoroughly enjoyed the show and left there in awe.

When I was 18 and new to the Army, I spent March 1995 in a one-month rotation at the National Training Center in Ft. Irwin, California. Remember when you could only fit so many cassettes- then CDs- in your luggage, your car, your backpack? "No Need to Argue" was one of the handful of cassettes I brought along. I remember like it was yesterday listening to that album as I lay in my sleeping bag on the floor of a clamshell helicopter hangar. That voice!


I listened extensively to the Vic Chesnutt album "About to Choke," containing the song "See You Around" in 1997, right at the time my high school friend Alec Vitarius collapsed and died from a brain aneurysm while working in the kitchen of his father's restaurant. That spring, I had stopped at Alec's college, looked him up and called him, then spent a memorable afternoon catching up and playing guitar. Two months later, just before reporting to West Point for the first time, I was on a trip to Germany with a friend when I heard Alec had died.

Alec was optimistic, ambitious, and unfailingly kind and friendly to everyone. Virtually our entire high school class attended his funeral. He loved sports, but the condition which led to his early death limited him to being a spectator. He loved baseball and the Yankees. In middle school, we were in the gifted program together and with our friends Antoinette, Kathleen, Scott, and others whose names I'm sure a glance at my yearbook would bring back in a flash, we had laughs in various creative pursuits. We sang "Puff the Magic Dragon" as a duet for a play tryout, adding doo-wop flourishes in the chorus. He got the part, I think it was "Man of La Mancha." We both had key roles in a different 7th (or 6th) grade play, and I remember the words to his songs better than my own. I remember those times, nearly 30 years ago, pretty vividly. Alec's mother Sharon had died of cancer a few years before him. After Alec passed, his father closed the family restaurant and moved away with his brother and sister.

At the funeral, I told his father "Alec was a good friend." "He still is a good friend," his dad replied, wanting me to keep a dead friend in the present tense. And he was right. Alec is a good friend. His optimism and academic curiosity set an example for me that helped me in college. He is a good friend. Like everyone we lose, I carry him with me as a memory and a blueprint of a life well lived. I have tried to be like Alec, and do things he didn't get to. And when Vic Chesnutt warbles the line "I'll see you around" over and over, I'm 20 years old again and listening to that song on the night I learned he died.

Such is the power of music and memory. I can go months without hearing those songs or having their attendant memories. But they're always in my head.

I sometimes scoff at the outpouring of grief at a rock star's death. "So what?" I say. "Their music is still there and their best years were behind them, anyway." Lately, though, I get it. These tormented souls made major contributions to the soundtracks of our lives. Their emotions become ours. "[O]ne must still have chaos within oneself to be able to give birth to a dancing star," Nietzsche wrote. The dancing stars are Michael Jackson songs, are Van Gogh paintings, Marlon Brando performances.

I don't have a conclusion, just a rumination on the perfectly legal opioids which killed many of these great singers. I had knee surgery in 2014. When I read the litany of potential side effects with the bottle of Hydrocodone the surgeon prescribed me, I decided that the devil I knew, "knee pain," was the better alternative. I don't know what physical, mental, or spiritual ailments drove these creative people to turn to drugs, but I am thankful my cross doesn't include them. I pray for the deceased, and I pray for you, dear friends. May you carry your own burdens with grace, and know that I love you, that many others love you, and that there is happiness and peace in your future.

"I do believe I'm getting old enough
To believe in better things."  
(who is alive and well)


Friday, January 19, 2018

What's in my Wallet?

So, credit cards can be a great way to get free travel, although they do have some downsides.

"Ok, Fox, what's in your wallet?" you ask in your Samuel L. Jackson or Jennifer Garner voice. Below is an inventory of the plastic (and metal!) I'm carryin' around right now, just like a rowdy credit card-totin' cowboy who just rolled into town and is lookin' to mix things up.

If you'd only killed him here, Sydney, he wouldn't have been able to ruin Batman, too. And y'all's marriage.


In my wallet

1. Chase Sapphire Reserve (CSR). I use this whenever I eat out (i.e. a lot) because it earns 3 points for every $1 spent on restaurants and travel (hotels, airfare, Uber, airport parking). When used as cash, each Chase Ultimate Reward (UR)  point is worth 1.5 cents. Due to math, 3 x 1.5 = 4.5; in other words, every dollar spent on lunch is worth 4.5 cents I can use toward airfare or hotels. $150 effective annual fee ($450 annual fee with $300 travel credit). Current bonus is 50,000 Chase UR points (worth $750. Got it? In addition to a host of other benefits you may or may not need, CSR also gets you a Priority Pass Lounge card for airport lounges. More details here.

2. American Express Blue Cash Preferred. Mrs. Fox carries this, actually. It earns a ridiculous 6% cash back at grocery stores (on up to $6,000 per year, then 1% after). 3% back at gas stations and select department stores (yes, they still have those), and 1% everywhere else. $95 annual fee, and this offer gets you $250 cash back after you spend $1,000 in the first three months.

3. *I am going to downgrade this card to the no-fee Hilton Honors card, which is 90% as good for my purposes. If it's your only card and you don't already have Hilton Gold status, its other benefits make it worth consideration: Hilton Honors Ascend. I commute 170 miles per day. I drive a Prius, but I still buy a lot of gas. 6 Hilton Points for every $1 on gas, as well as supermarkets and restaurants, but I only use mine for gas and miscellaneous (3 points per $1) as CSR and Blue Cash are better options for restaurants and groceries, respectively. It earns 12 Hilton points per $1 at any of Hilton's hotels. For reference, 20-30k Hilton points will get you a free night. Annual fee is $95, currently with a 75,000 bonus (spend $2k within 3 months) with potential for another 25,000 when you spend an additional $1,000 within six months of the card's opening.

4. Chase Sapphire Preferred (CSP). This is CSR's little cousin. It's similar to the CSR, but earns 2 points instead of 3 on travel categories. One person can't have both of Chase's premium Sapphire cards; you have to pick one, so this is Mrs. Fox's. She uses it at restaurants for 2 Chase UR points per $1 spent. Redemptions in the Chase Travel Portal are at 1.25 cents per UR point, but she can transfer her points to me and I'll get 1.5 cents per point. We just used this to pay for kid #3's braces: minimum spending taken care of in one fell swoop! Mrs. Fox is very helpful with meeting credit card minimum spending requirements, bless her! The annual fee is $95 but waived the first year with this offer. Like CSR, you currently get 50,000 UR points (worth $625) when you spend $4,000 in the first three months.

5. Mrs. Fox also has a USAA cash back card that gets 1.5% cash back on everything. It's good for miscellaneous purchases like new tires, TJ Maxx and, uh, LuLaRoe. Lots of that. In select states, USAA has a sweet-looking 2.5% unlimited cash back card. Not in my state, unfortunately.

In a drawer

Many of these cards provide benefits for having the account, like priority boarding, a free checked bag, and various hotel status/perks. I don't necessarily need to use them because whatever I'm buying, the cards that are in my wallet earn more points/miles/cashback. Will discuss each in more detail in forthcoming posts. These have links, some of which give me bonus points if you sign up using my links.

6. American Express Platinum. Like my inner party animal, this card only comes out when I travel.

7. Chase Marriott Rewards Visa. Got the points, no need to use it now. Mrs. Fox has one too, which I will cancel soon. $85 annual fee and a free night every year after Year One.

8. Chase IHG Rewards Club MasterCard. See above. Good benefits for having the card, but no need to use it anywhere once I got the bonus. Low fee ($49, waived first year) and like above, one free night per year on the anniversary.

9. Chase Amazon Prime Rewards Visa. Great card, all my Amazon shopping goes on it. 5% cash back on Amazon purchases as a Prime member. No annual fee.


10. Chase United Mileage Plus Explorer Visa. Great card; I fly United a lot. Gives me access to more award seats, free checked bag, boarding group 2 (so there's still overhead space). $95/year fee, waived the first year, 50,000 mile bonus.

11. American Express Delta SkyMiles Platinum. Just got it and the 70,000 Delta miles that came with it. $195 annual fee. We loves us some flyin'!

12. Discover It. This card has rotating quarterly 5% cashback for various categories like gasoline, Amazon, and groceries- stuff I can get better returns on with the cards in my wallet. I don't have time to fool with that. Might be a good deal if you can find a 0% offer. Oh Lord Jesus, it's got no annual fee! 


What I don't have

A fox knows many things, but he doesn't know everything: these cards are blind spots for me.

1. Any Citibank cards. I had a Citi no-fee Hilton card, but their contract with Hilton ended and now Amex has all the Hilton cards. Citi has superior extended warranty protection over other card issuers. They extend an item's warranty two years, vs. the standard one year. In 2009, the first HDTV I owned quit working a few months after the warranty expired and Mastercard covered the $400 repair under extended warranty coverage. Citi also have the Citi ThankYou Premier card to compete with Amex Platinum and Chase Sapphire Reserve.

2. Any Capital One cards. I don't know much about these, but every offer I see doesn't impress me. They're spending their money paying Elektra and Ezekiel 25:17 guy to ask the question that is the title of this post.

3. Amex Starwood Points Group Card. I want this one, but I'm waiting for the sign-up bonus to go up. Currently it's 25,000 but it's been 35,000 in the past.

4. There might be something really cool that I don't even know about. Let me know in the comments if there's a card you love. A good fox is always willing to learn!

"What's in YO wallet, mutha.....?"

Every Rose Has its Thorn: Downsides

I've tried to lay out the positives of the Credit Card Game. However, as Poison knows, every rose has its thorn. There are a few things to remember before diving in:


1. You have to pay them off every month. If you are late even one day on the payment, you're looking at 15-25% annual interest. 
So: PAY. THEM. OFF.  If there's any possibility you won't be able to pay the bill off monthly, don't get them.

2. Frequent credit checks and new accounts will slightly reduce your credit score. The credit bureaus use an opaque formula so it's not exact, but if you start out with a 700+ credit score, you'll be fine. By the way, every year you can get a credit report for free from each of the three main credit bureaus, by law, at www.annualcreditreport.com. Many credit card companies also offer free credit scores and reports.

3. Chase's "5/24 rule": if you've opened five new credit cards (from any issuer, not just Chase) in the past 24 months, Chase won't approve you for a new card. Some Chase cards don't count toward 5/24; details here: Implied task: get your Chase cards first.

4. It is a bit of work. As I've written before, I treat it as a side job: I spend a few minutes daily checking my balances and ensuring I schedule payments on 5-8 cards at any given time (the rest are in a drawer). In exchange, I get tangibly valuable things like hotel rooms, free flights, and cash back. I read about people using spreadsheets and online services to track all their card, and I don't understand this because you should only have 3-4 cards in regular use (more on this in the future). All that said, for some people it might be a hassle, or even a source of stress. So if it seems that way to you, don't bother with it! Life is short. But if you're smart, you'll earn enough cash back to buy enough Aquanet to keep the entire Poison lineup's hair voluminous through every glorious night of the Monsters of Rock Arena Tour.
Although we both lie close together, we feel thousands of frequent flyer miles apart inside.
5. The Dave Ramsey philosophy ("I H8 DEBT"). I understand and respect that some people (including people I know and admire) want to pay cash for everything, pay off their house as quickly as possible, and cut up their credit cards . They get great peace of mind, perhaps because they've struggled with debt in the past or just want a stress-free life. We all have friends and family with debts that are kicking their butts. I look at debt as a tool, something you use to make life easier. I use my credit cards to make money (and the "work" part feels more like a game to me: I am, after all, a wannabe clever fox). I also recognize that I am blessed with better job security than most people in the modern economy.

6. If you plan to get the card, spend the minimum, get the points/miles, and then close the account, it will also slightly hurt your credit. A better option is a "product change": asking the issuer (e.g. Amex) to switch that account (and its credit history) to another one of their cards. The downside of that? No sign-up bonus.
Like a knife that cuts you, the credit score heals. But the scar, that scar will remain (it actually doesn't, now take it away with a guitar solo, C.C. DeVille!)

7. Every good card has an annual fee, ergo each card has a break-even point below which it isn't worth keeping. Don't fly often? Might not be worth the $95 annual fee on that airline credit card--after, of course, the first year when you get XX,000 miles for that $95.
I know I could've saved some cash that night if I'd've known what to say/ Instead of makin' love/ me and this credit card both made our separate ways. 

8. Devaluations. As everyone who blogs about this will tell you, miles and points are a bad long-term investment. Think Zimbabwe-style inflation. There's a big frenzy among credit card issuers to get people using their cards, and a virtual arms race to award more points and more miles. Airlines and hotels love it, because the credit card companies pay them for ephemeral points that they constantly devalue by raising award redemption rates and adding restrictions. And you though Bitcoin was built on sand! For example, until February 2017, I could get rooms at nice Hilton properties for $40+8,000 points. When Hilton "improved" their program, the same room was about $60+15,000 points. So overnight, Hilton points were worth about half what they were before. This is known as a "stealth devaluation." Hilton makes Ben Bernanke look like a piker with his quantitative easing. Lesson learned: if your loyalty program emails you to tell you about "exciting new improvements," run like hell, spend the points, and make love to the first person you see because the world's ending!

So what does this mean to me, Fox? 

Get each card with a specific goal in mind, such as: "I am going to fly myself and my three older children to Europe this summer." This is actually my goal. I'll use my United miles, transfer Chase Ultimate Rewards into more United miles, and only pay the taxes on each flight.

Bottom line: know what you're getting into, and don't be like every cowboy who sings a sad, sad song. To hear that would tear me up inside. Can you think of any other downsides? Got questions? Feel free to email me or comment below. Rock on!

My actual tattoo. If you haven't seen it, you don't know me well enough.

Fun digression: this was the first song I learned to play on guitar, not to mention a middle school dance staple.